Faculty panel at institutional risk forum

Meet the Faculty.

Every instructor on this program has held a senior risk or treasury position at a Tier-1 bank, central bank, or prudential regulator before joining the program faculty. None are career academics. Each brings active institutional experience that connects regulatory theory directly to the pressures of a real treasury desk or supervisory review cycle.
  1. 01

    Institutional Backgrounds

    Faculty members have served as senior officers at Tier-1 commercial banks, central banks, and national prudential regulators across multiple jurisdictions, including Australia, the United Kingdom, and continental Europe.
  2. 02

    Active Practitioners

    Each instructor maintains active engagement with funding liquidity risk through consulting, regulatory advisory roles, or institutional research — ensuring that program content reflects current market and supervisory conditions, not historical frameworks alone.
  3. 03

    Regulatory Expertise

    Several faculty members contributed directly to the development or review of national liquidity standards, including frameworks aligned with Basel III LCR and NSFR requirements, providing participants with interpretive depth that published standards alone cannot supply.
  4. 04

    Published Authors

    Faculty members have authored peer-reviewed research, regulatory consultation submissions, and practitioner-focused analytical papers covering funding gap measurement, collateral management, and contingency funding plan design across multiple institutional contexts.
Lead Instructors and Subject-Matter Experts in Liquidity Risk

  1. 01 Former Head of Liquidity Risk, Reserve Bank
    Dr. Margaret Ellison, Lead Program Director and Senior Faculty

    Dr. Margaret Ellison, Lead Program Director and Senior Faculty

    Dr. Ellison spent over a decade as Head of Liquidity Risk at a central bank, where she oversaw the design and implementation of intraday liquidity monitoring frameworks aligned with Basel Committee guidance. Her published research on funding gap dynamics in leveraged institutions has been cited in prudential consultation papers across three jurisdictions. At Byolcervaezialto, she leads the module sequence on LCR mechanics and regulatory ratio construction, drawing on specimen data from her supervisory career to anchor each quantitative exercise in realistic institutional context.

  2. 02

    Former Managing Director, Treasury Risk, Tier-1 Bank
    James Hartley, Senior Instructor, Collateral and Funding Markets

    James Hartley, Senior Instructor, Collateral and Funding Markets

    James Hartley served as Managing Director of Treasury Risk at a major international bank for more than a decade, with direct responsibility for repo market operations, collateral pool management, and stress scenario calibration during the 2011 European sovereign debt period. His practical experience with haircut mechanics and collateral velocity measurement informs the entirety of module four, where participants trace how collateral quality deterioration transmits stress across secured funding markets. He has presented at institutional risk conferences in Sydney, London, and Frankfurt.

  3. 03

    Former Prudential Analyst, APRA Liquidity Policy
    Dr. Priya Subramaniam, Instructor, Regulatory Frameworks and APRA Standards

    Dr. Priya Subramaniam, Instructor, Regulatory Frameworks and APRA Standards

    Dr. Subramaniam held a senior analytical role within the liquidity policy division of Australia's prudential regulator, where she contributed to the domestic implementation of the Net Stable Funding Ratio under APS 210. Her detailed knowledge of how APRA applied Basel III discretions — and where Australian standards diverge from international norms — gives module three a level of jurisdictional precision that generic Basel III commentary cannot provide. She currently advises deposit-taking institutions on NSFR compliance methodology and ILAAP documentation.
  4. 04

    Former Chief Risk Officer, Mid-Tier Bank, Australia
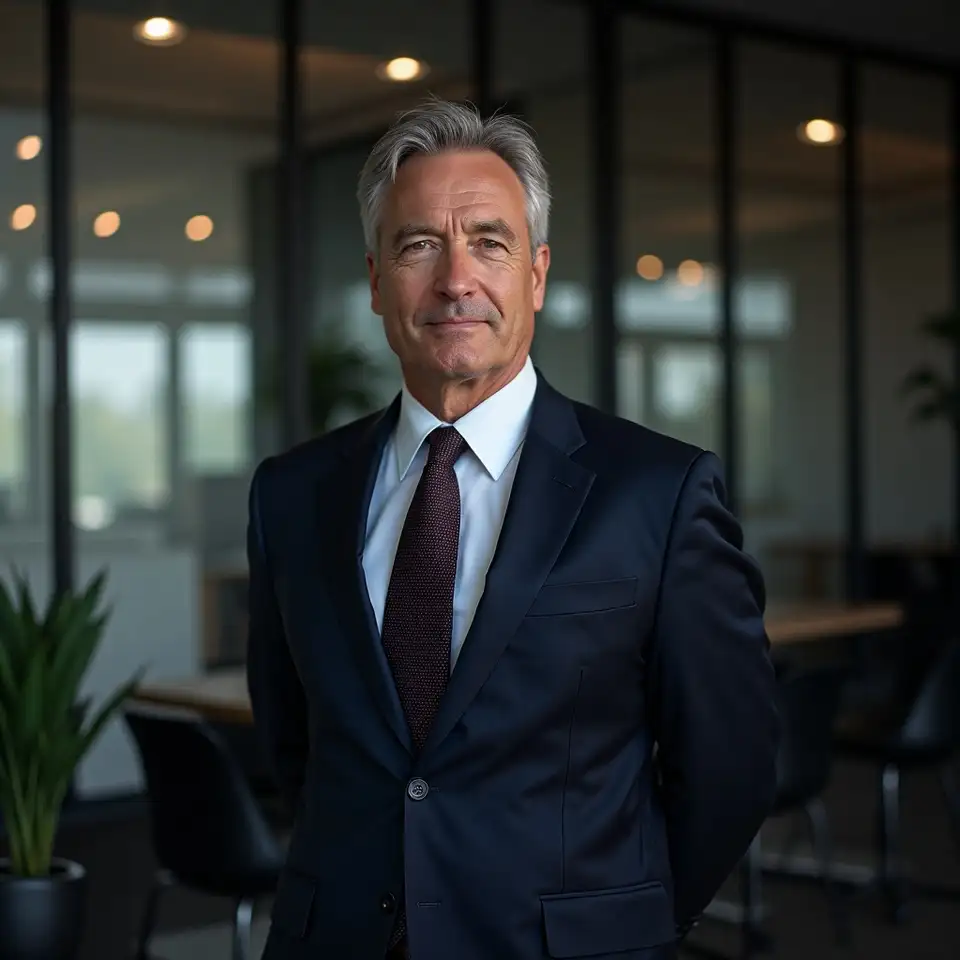
    Thomas Bauer, Instructor, Contingency Funding and Stress Testing

    Thomas Bauer, Instructor, Contingency Funding and Stress Testing

    Thomas Bauer served as Chief Risk Officer at a mid-tier Australian bank across two economic downturns, during which the institution's contingency funding plan was activated and subsequently revised under supervisory direction. That direct operational experience shapes module six entirely. Participants engage with CFP design not as a documentation exercise but as a technical stress-testing discipline, using trigger calibration frameworks and escalation governance structures drawn from Bauer's institutional practice. He holds an appointment as an adjunct researcher at a leading Australian university.
  5. 05

    Former Payments Risk Specialist, Central Bank
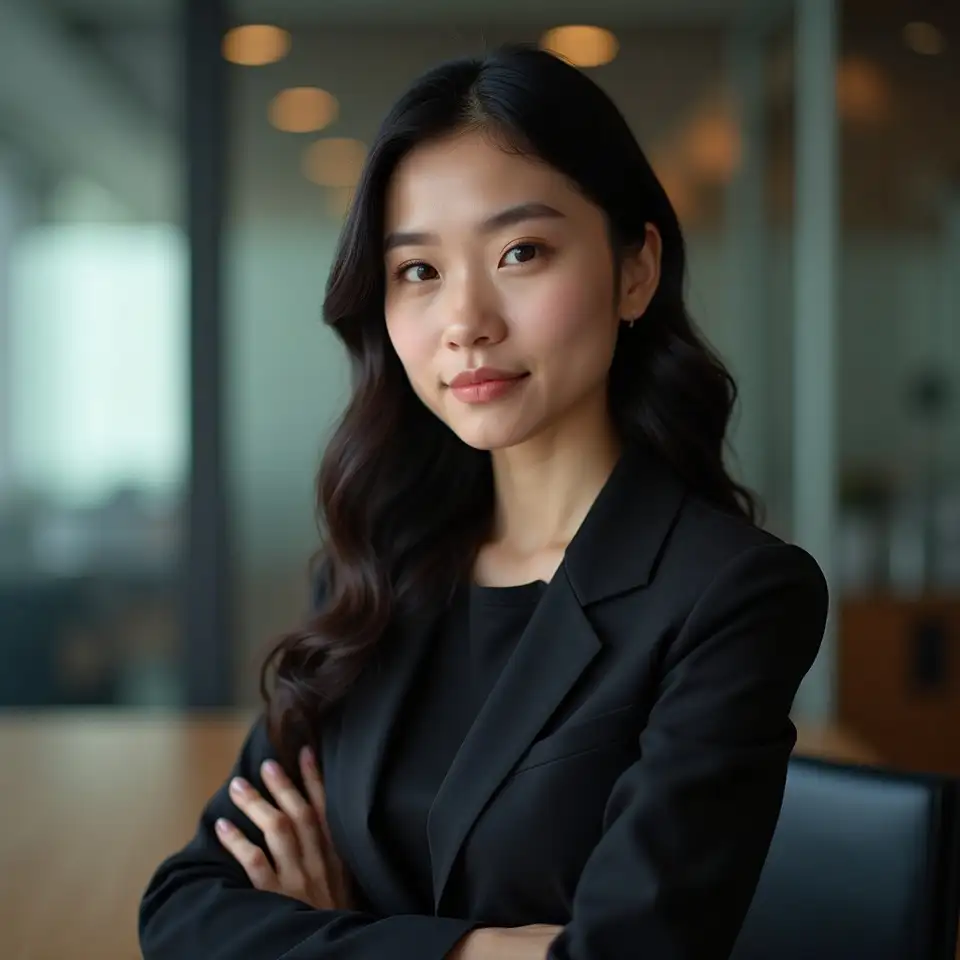
    Dr. Yuki Tanaka, Instructor, Intraday Liquidity and Payment Systems

    Dr. Yuki Tanaka, Instructor, Intraday Liquidity and Payment Systems

    Dr. Tanaka spent her central bank career analysing intraday liquidity flows across real-time gross settlement systems, with a specific focus on the relationship between reserve balances and payment timing behaviour under stress. Her module five delivery draws on monitoring data and system design documentation from the Australian high-value settlement environment, making the abstract concept of intraday risk concrete through operational case references. She has contributed written analysis to Basel Committee working groups on intraday liquidity monitoring metrics.
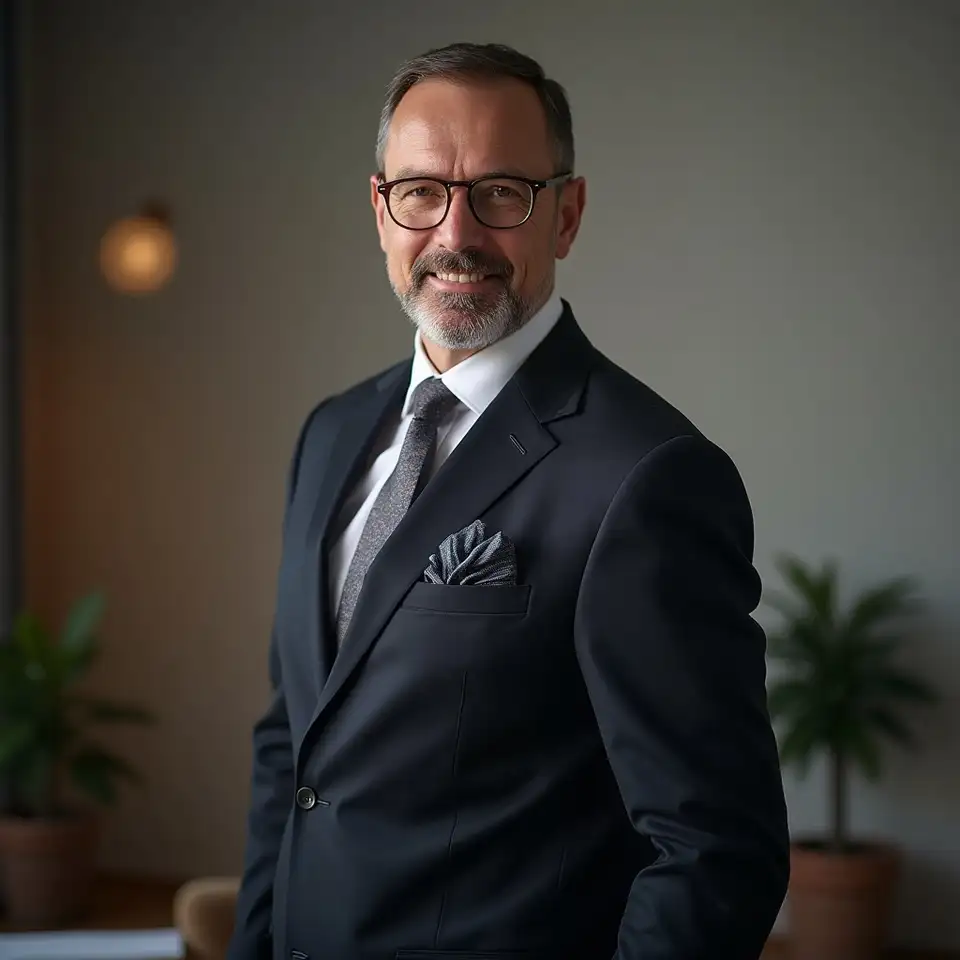
  6. 06 Former Portfolio Risk Director, Investment Bank
    Richard Calloway, Instructor, Leveraged Portfolio Risk and Market Interaction
    Richard Calloway, Instructor, Leveraged Portfolio Risk and Market Interaction

    Richard Calloway led portfolio risk analysis at an international investment bank, focusing on the interaction between market liquidity deterioration and funding liquidity stress in leveraged balance sheets. His work during the 2007 to 2009 stress period produced internal research on maturity mismatch amplification that was later incorporated into the firm's revised internal liquidity adequacy assessment. At Byolcervaezialto, he integrates this market-funding interaction into the capstone module, requiring participants to account for both dimensions simultaneously when proposing structural balance sheet adjustments.

Faculty Recognition and Institutional Contributions

Basel Committee Analytical Contribution Award

Faculty member Dr. Yuki Tanaka received formal recognition from a Basel Committee working group for written contributions to the development of intraday liquidity monitoring metrics, acknowledged in the published committee report on payment system risk.

APRA Liquidity Policy Acknowledgement

Dr. Priya Subramaniam received an internal regulatory acknowledgement for her role in drafting the consultation analysis that informed Australia's domestic NSFR implementation under APS 210, cited in the final prudential standard release documentation.

Featured Speaker, International Risk Forum

James Hartley delivered the keynote address on collateral velocity and secured funding market dynamics at an international institutional risk conference, with the published summary referenced in subsequent BIS working papers on repo market stress.

Published Research, Journal of Banking Regulation

Dr. Margaret Ellison authored a peer-reviewed paper examining the interaction between LCR compliance behaviour and central bank repo facility usage during acute funding stress, published in a leading journal covering prudential policy and banking regulation.

Prudential Risk Educator Recognition

The Byolcervaezialto faculty panel received recognition from an Australian finance industry body for the quality and institutional rigour of its liquidity risk analytical content, distinguishing practitioner-led delivery from standard academic treatment of regulatory frameworks.

Cross-Jurisdictional Regulatory Advisory Roles

Multiple faculty members have served in formal or informal advisory capacities to prudential regulators in Australia, the United Kingdom, and the European Union on matters relating to liquidity risk measurement methodology and stress scenario calibration standards.

Practitioner-Grade Liquidity Risk Analysis Demands Instructors Who Have Lived the Stress

The defining characteristic of this faculty is not academic credential — it is institutional memory. Each instructor has sat inside a treasury or supervisory function during a period of genuine funding pressure, and that experience determines what gets taught and how the analytical frameworks are presented to participants.
Collateral management cannot be taught purely through haircut tables. The 2011 sovereign debt episode demonstrated that eligible collateral can become systemically problematic in the very moment it is most needed. Participants in module four engage with that circularity as an analytical problem, not as a historical footnote.
    Senior Instructor, Collateral and Funding Markets
APRA's implementation of the NSFR diverges from the Basel baseline in ways that matter significantly for Australian deposit-taking institutions. Those divergences are not prominently flagged in most analytical summaries. Module three addresses them directly, using the actual APS 210 text as the primary reference throughout.
Instructor, Regulatory Frameworks and APRA Standards
Intraday liquidity risk is invisible until it is not. Payment timing behaviour under stress reveals structural vulnerabilities that end-of-day ratio snapshots entirely miss. Module five exists because the Basel Committee identified this gap formally, and Australian institutions are now expected to monitor and report against it.
    Instructor, Intraday Liquidity and Payment Systems
The capstone module requires participants to account for market liquidity and funding liquidity simultaneously. That interaction is not a theoretical refinement — it is the mechanism through which a manageable funding gap becomes an acute institutional crisis. Analytical frameworks that treat the two as independent are insufficient for leveraged balance sheets.

    Instructor, Leveraged Portfolio Risk and Market Interaction

Alumni Perspectives

What Finance Professionals Say About the Faculty and Program Delivery

Sarah Drummond treasury risk professional

Sarah Drummond

Treasury Risk Manager, Major Australian Bank
5.0
“The LCR module was delivered by someone who had actually designed a central bank monitoring framework. The difference between that and a textbook walkthrough is substantial. The interpretive questions — where APRA diverges from Basel — were handled with precision that no published summary provides.”
David Nguyen prudential risk analyst

David Nguyen

Prudential Analyst, Regulatory Body
4.9
“Module six on contingency funding plan design was the most practically useful analytical exercise encountered outside actual supervisory work. The instructor's account of receiving a regulatory direction to revise a live CFP gave the session a credibility that structured scenarios alone cannot replicate. The trigger calibration framework is now applied directly in current work.”
Claire Okonkwo senior credit risk officer

Claire Okonkwo

Senior Credit Risk Officer, Investment Bank

4.8
“The collateral management module addressed something no prior analytical program had covered adequately — how collateral velocity amplifies stress transmission. The 2011 European case was examined with enough institutional detail to make the mechanism genuinely legible, not just narratively interesting.”
Michael Brennan balance sheet manager

Michael Brennan

Balance Sheet Manager, Regional Bank
4.9
“The faculty's practitioner backgrounds became most apparent during the capstone module, where the interaction between market liquidity deterioration and funding stress had to be addressed simultaneously. The analytical feedback on the submission identified specific gaps in the structural adjustment proposals that a purely academic reviewer would not have detected.”
Anika Patel liquidity risk specialist

Anika Patel

Liquidity Risk Specialist, Asset Management Firm
4.8
“The APRA-specific content in the NSFR module made this program significantly more relevant to Australian institutional practice than alternatives reviewed. Dr. Subramaniam's direct involvement in the domestic implementation of APS 210 produced a level of jurisdictional detail that simply cannot be replicated from published documentation alone.”
Sarah Drummond treasury risk professional

Sarah Drummond

Treasury Risk Manager, Major Australian Bank
5.0
“The LCR module was delivered by someone who had actually designed a central bank monitoring framework. The difference between that and a textbook walkthrough is substantial. The interpretive questions — where APRA diverges from Basel — were handled with precision that no published summary provides.”
David Nguyen prudential risk analyst

David Nguyen

Prudential Analyst, Regulatory Body
4.9
“Module six on contingency funding plan design was the most practically useful analytical exercise encountered outside actual supervisory work. The instructor's account of receiving a regulatory direction to revise a live CFP gave the session a credibility that structured scenarios alone cannot replicate. The trigger calibration framework is now applied directly in current work.”
Claire Okonkwo senior credit risk officer

Claire Okonkwo

Senior Credit Risk Officer, Investment Bank
4.8
“The collateral management module addressed something no prior analytical program had covered adequately — how collateral velocity amplifies stress transmission. The 2011 European case was examined with enough institutional detail to make the mechanism genuinely legible, not just narratively interesting.”
Michael Brennan balance sheet manager

Michael Brennan

Balance Sheet Manager, Regional Bank
4.9
“The faculty's practitioner backgrounds became most apparent during the capstone module, where the interaction between market liquidity deterioration and funding stress had to be addressed simultaneously. The analytical feedback on the submission identified specific gaps in the structural adjustment proposals that a purely academic reviewer would not have detected.”
Anika Patel liquidity risk specialist

Anika Patel

Liquidity Risk Specialist, Asset Management Firm

4.8
“The APRA-specific content in the NSFR module made this program significantly more relevant to Australian institutional practice than alternatives reviewed. Dr. Subramaniam's direct involvement in the domestic implementation of APS 210 produced a level of jurisdictional detail that simply cannot be replicated from published documentation alone.”